Beijingwalker
VIP Member

Is China’s industrial overcapacity the last line of defence against US inflation?
11 November, 2026Monday’s US CPI exceeded expectations by +50%, reaching +0.3% MoM in Oct’26, putting inflation back in central banks’ spotlight.
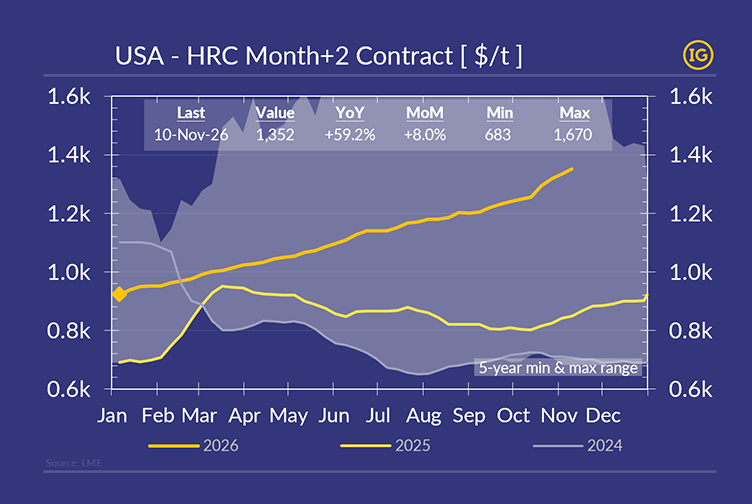
Oil is a common inflation proxy, but steel is equally revealing. Hot-Rolled Coil prices, a key manufacturing input, have surged +59% YoY in the USA.
Since 2010, three deflationary forces have contained inflation despite successive rounds of quantitative easing: automation, expanding fossil fuel production (notably US shale oil), and China’s industrial overcapacity.
Today, AI investment fuels inflation while fossil fuel supply remains constrained. Only China’s industrial overcapacity, exporting over 10 Mt/month of steel in Oct’26 alongside other manufactured goods, remains a major deflationary force.
The dilemma: protect local industries (where they exist) or import cheaper Chinese goods to contain inflation. A bullish prospect for geared bulk carriers, carrying Chinese steel and other energy-intensive manufactured goods to help extinguish the inflation fire!